Behavioral models built for your balance sheet, not the industry's.
Empyrean Model IQ™ is behavioral modeling software for deposits, loans, and credit. It replaces vendor defaults and consultant studies with institution-specific models built from your own data and kept current as that data changes.
Trusted by more than 700 institutions
Your data. Your assumptions. One platform.
Empyrean Model IQ™ is behavioral modeling software for deposits, loans, and credit. It replaces vendor defaults and consultant studies with institution-specific models built from your own data, and kept current as it changes.
Your balance sheet, actively managed, not periodically reported.
Deposit IQ.
Model deposit decay, beta sensitivity, and early withdrawal behavior including cannibalization analysis to separate new growth from internal balance transfers.
Loan IQ™.
Instrument-level loan prepayment modeling, with methodology that flexes by product type, so prepay speeds reflect your actual loans.
Credit IQ™.
Credit loss and recovery modeling from your own net charge-off history, using NCO, CECL, or PD/LGD.
Calibrated on your own book.
Models built from your own historical data rather than published industry averages, so every assumption traces back to a segment of your balance sheet.
Living models.
Signal-driven rather than schedule-driven. Assumptions stay current as your data updates, so you're never running ALM on a number that was accurate two years ago.
A glass box, not a black box.
Assumption documentation and a full audit trail are built in as models are calibrated, so nobody has to guess why the deposit beta changed this quarter.
Four ways to get a deposit beta. Only one of them stays current.
Vendor defaults give you an average. Consultants give you a snapshot. Model IQ gives you a living model built from your own data.
Where an assumption comes from decides whether your NII, EVE, and allowance reflect your balance sheet or someone else’s.
Vendor defaults are free, which is why most banks start there. The cost shows up later, in the distance between a published average and how your own depositors actually behave, and it lands in your NII and EVE.
Your assumptions and your ALM, on one platform.
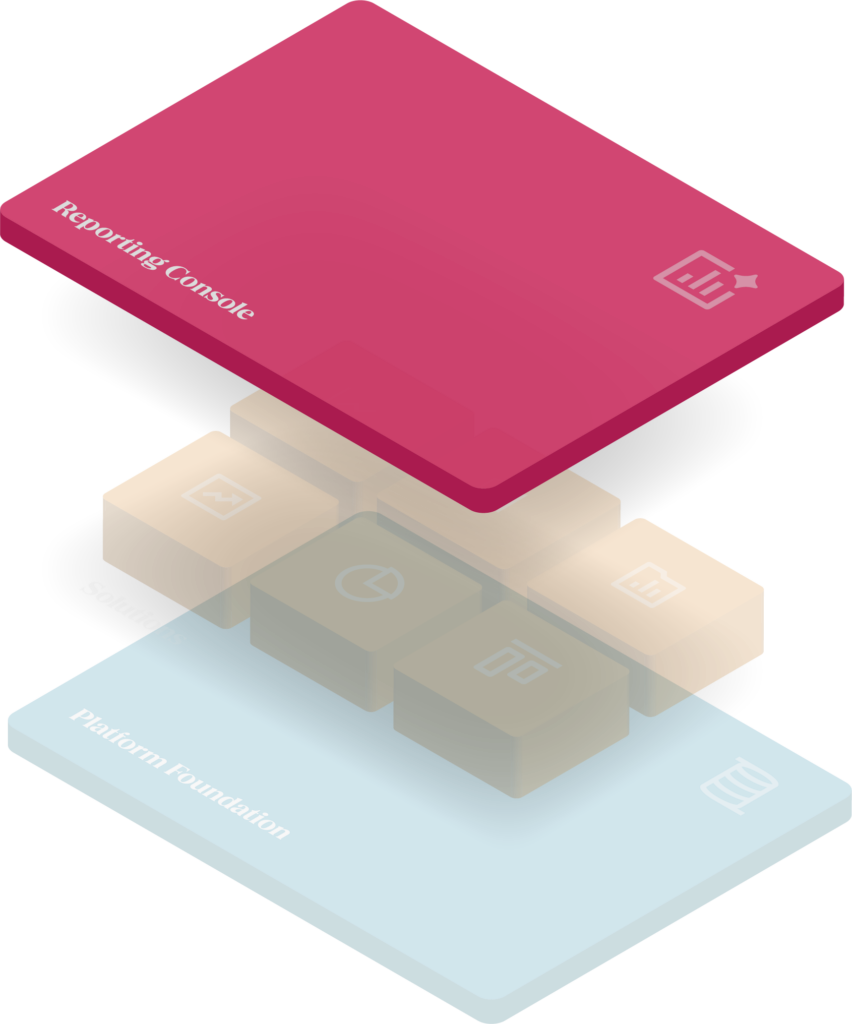
Model IQ isn't an external study you import. It runs natively in Empyrean Dataverse, the single platform behind Empyrean ALM, FTP, and CECL, so the deposit betas in your NII and EVE, the FTP your treasury team prices to, and the loss curves in your allowance are all the same calibrated model.
No separate data management, no re-keying, and no gap between what one system reports and what another one says.
Your environment, with open architecture
On another ALM platform? The behavioral models still calibrate from your own data and come with documentation. The native integration into NII, EVE, FTP, and CECL is built for Empyrean ALM. If you’re on QRM, SS&C, or another platform, talk to your Empyrean representative about how Model IQ fits your environment.
See how we can help you model your own deposits, loans, and losses, from your own data, not a vendor's.
A $3B bank and a $30B bank don't run the same ALM shop.
Behavioral modeling looks different at a $3B community bank where one team owns ALM start to finish than it does at a $30B regional with a model risk function and a validation queue. So does the way Model IQ fits.
Professional behavioral modeling, without the quant team.
Model IQ builds the models from your own data and feeds them into your Empyrean ALM automatically, so your assumptions are yours, current, and grounded in your own numbers.
Your data, your models, your accuracy
Generic deposit and prepayment assumptions are averages, not your depositors, and your NII and EVE results inherit the gap. Model IQ replaces the borrowed assumption with an empirical model built from your own deposit, loan, and credit history, kept current as your data updates, so the gap closes and stays closed.
Model your own depositors.
Retire the periodic study.
No import button.
Documentation built in.
Built for the team you actually have
Your ALM team is small, and a real share of its time goes to assembling deposit and loan data rather than interpreting it. Model IQ runs institution-specific behavioral models without a data-science team or a standing consulting engagement, so your accuracy doesn't wait on headcount you don't have.
Start with Deposit IQ.
No quant team required.
Right-sized.
One assumption set across ALM, FTP, and CECL.
Deposit, prepayment, and credit models all calibrate from your own data on one platform, so your model validation team reviews a single assumption set instead of three separate studies. Every cycle starts from the same calibration, which leaves no gaps between studies for errors to hide in.
Accurate assumptions across deposits, loans, and credit.
Clear model validation faster.
Stop reconciling numbers across systems.
Match the granularity your balance sheet needs.
Free your quant team from data wrangling.
Never stall on a thin or new segment.
Calibrated once, consistent everywhere
Model IQ runs natively inside Empyrean Dataverse, so the beta behind your NII run, the rate your treasury team prices to, and the curve behind your allowance all resolve to one calibration instead of three numbers you reconcile before the board meeting.
It’s a single source of truth for your behavioral assumptions.
Your data, your governance
Assumption change tracking is built into the platform as your models are calibrated, with more of that work automated as the platform evolves.
Compliance readiness comes out of the architecture rather than a separate exercise, and your validation queue starts from evidence instead of a scramble.
Sized for where you're going
Frequently asked questions
-
Behavioral modeling is how you predict your own balance sheet’s behavior. It estimates how a bank’s deposits, loans, and credit will actually behave: how non-maturity deposits reprice and run off, how loans prepay, and how credit losses and recoveries develop. Those behaviors drive your ALM, FTP, and CECL. Empyrean Model IQ calibrates the models empirically from your own historical data across three modules (Deposit IQ, Loan IQ, and Credit IQ), documents them as they’re built, and feeds the results directly into Empyrean ALM, FTP, and CECL on one platform.
-
A deposit beta measures how much of a change in market rates a bank passes through to its deposit rates. It’s one of the most consequential and most scrutinized assumptions in an ALM model, because it drives NII and EVE under rate shocks. Most banks rely on a published or vendor-default beta that reflects the industry, not their depositors. Deposit IQ calibrates betas, along with decay, stability, and renewal rates, from your own deposit history, so your rate-risk results reflect how your customers actually behave.
-
Your NII and EVE results are only as accurate as the deposit and prepayment assumptions behind them. When those assumptions are published industry averages or a study from a few years ago, the error carries through every rate-shock report. Model IQ replaces them with betas, decay rates, and prepayment speeds calibrated from your own data and kept current, so the inputs reflect how your customers actually behave.
-
A model is only as good as the evidence behind it. Does it reflect your institution, is the methodology documented, and can you show your work? Model IQ calibrates from your own data, produces documentation alongside the models as they’re built, and keeps a full assumption audit trail, so your model validation team has evidence to review instead of a study to reverse-engineer.
-
SR 26-2 is the Federal Reserve, OCC, and FDIC’s revised interagency guidance on model risk management, issued April 17, 2026, replacing the SR 11-7 framework from 2011. The agencies note it’s expected to be most relevant to institutions above $30 billion in total assets, while also emphasizing that model risk management practices should scale to an institution’s size, complexity, and risk profile. That scaling language matters for growing community and regional banks even where the letter isn’t written for them. Whatever guidance applies to you, the underlying expectation is consistent: models should be built on your own data, documented, and explainable. Model IQ calibrates from your own history, documents assumptions as they’re built, and keeps a full audit trail.
-
A consultant study and a standalone analytics tool both give you institution-specific results, but as a point-in-time deliverable that you then move into your ALM workflow by hand, and that ages until the next study. Model IQ is a living platform. The models stay current as your data updates, and the outputs feed Empyrean ALM, FTP, and CECL directly, with no separate data management or manual transfer.
-
For many smaller or simpler portfolios, vendor defaults may still be sufficient, and we’ll tell you if that’s the case. The pattern worth watching is the distance between a published average and your actual deposit behavior, which tends to widen as a book gets more complex or more relationship-driven, and that distance shows up directly in your NII and EVE. Model IQ gets you to an institution-specific model faster than building one from scratch, and it holds up whenever the question comes up, whether that’s from your model validation team or an examiner.
-
Yes, with a distinction worth understanding. The underlying models, meaning institution-specific deposit, prepayment, and credit calibrations with full documentation, aren’t tied to any single ALM platform. What’s built specifically for Empyrean ALM is the native, automatic integration of those outputs into your NII, EVE, FTP, and CECL runs. If your ALM runs on QRM, SS&C, or another platform, talk to your Empyrean representative about the best way to put Model IQ’s calibrations to work in your environment.
-
Yes. That’s who Deposit IQ is built for. The methodology, calibration from your data, and the documentation are built into the platform, so a lean ALM or treasury team can produce and maintain institution-specific models without dedicated quant staff or a standing consulting engagement.
-
It can. Model IQ doesn’t take methodological control away from a quant team. It carries the data-management and documentation burden and adds peer benchmarking your internal build won’t have. For teams committed to building everything in-house, that’s a fair reason to wait, though the documentation and benchmarking are often the parts worth not rebuilding.
-
Yes. Where your own history is thin or a product segment is new, Model IQ uses peer data to calibrate and to cross-validate the models you do build from internal data, so you’re not stuck choosing between a generic default and no model at all.
-
It depends on how much history you have and whether you’re already an Empyrean customer. Existing Empyrean ALM, FTP, or CECL customers move fastest, since the data and integration are already in place. The work is calibrating the models from your history, validating them, and connecting the outputs to your production runs. Most teams start with Deposit IQ, calibrate from their deposit history, validate against a recent period, then feed the models into ALM.
-
Model IQ is an add-on to your Empyrean platform, scoped to the modules you need (Deposit IQ, Loan IQ, Credit IQ). What it costs depends on your institution and the modules in scope, so the next step is a scoped quote from your Empyrean representative.